Danaher: growth is not one number
By @engtmk · Research as of 21 October 2026
On Monday, JPMorgan’s headline profit needed a closer look at its comparison base and supports. Today’s Danaher results raise a related question: how much does the headline sales number tell us about the underlying business?
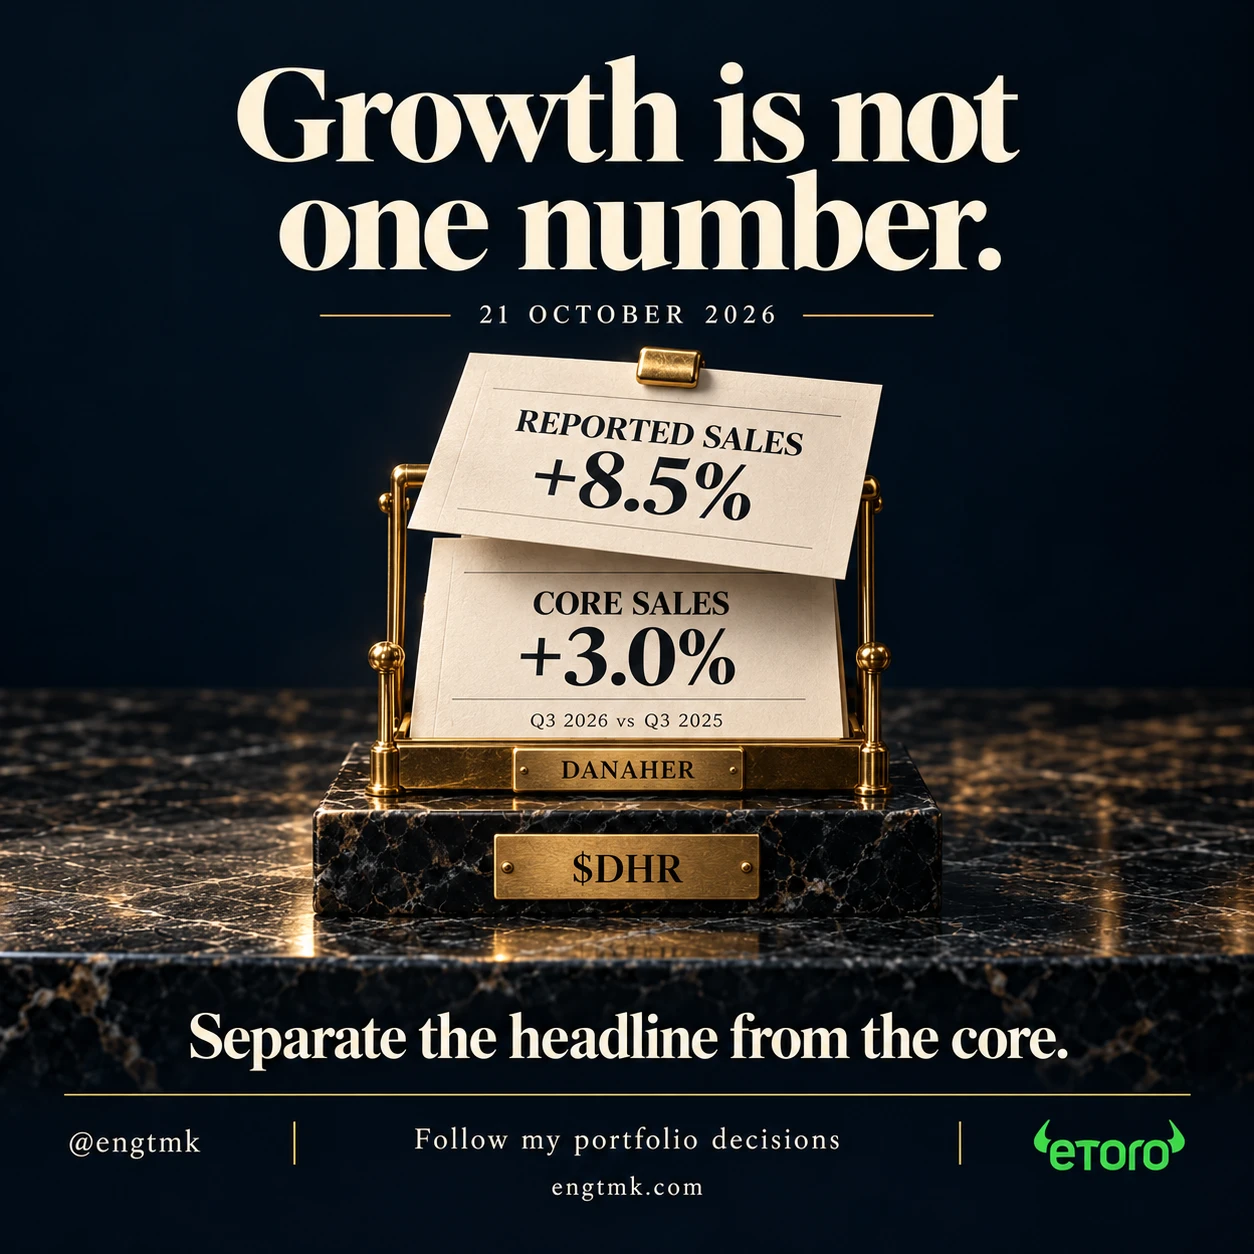
This expands today’s published eToro post. The conclusion is not that growth is absent. It is that acquisitions, a changed adjustment and uneven segment performance make one number an incomplete investment case.
First, reconcile the growth
Danaher’s 21 October earnings release and reconciliation covers the three months ended 25 September 2026, compared with the corresponding 2025 period. All growth comparisons below are year on year unless stated otherwise; guidance is not an actual result.
The company reports 8.5% sales growth and 3.0% non-GAAP core sales growth. Its rounded reconciliation is:
| Q3 growth bridge | Percentage points |
|---|---|
| Reported sales growth | 8.5 |
| Remove acquisitions/divestitures | −6.5 |
| Currency adjustment | 0.0 |
| Exclude tariff refunds to customers | +1.0 |
| Core sales growth | 3.0 |
These are the company’s rounded figures, not an independently calculated growth rate from dollar sales. The 5.5-point reported-to-core gap is not an acquisition-only adjustment: removing 6.5 points and adding back one point gives the net difference.
The refund treatment is new this quarter. Danaher now excludes from core growth tariff refunds it received for prior-period payments that are returned or to be returned to customers. This is not simply extra current-period customer demand. It is also not evidence that every difference between reported and core growth is artificial or unimportant.
For an investor, the bridge separates growth acquired through changes in the business perimeter from the company’s chosen view of underlying growth. Both matter, but acquired revenue still needs to earn an adequate return on the capital used to obtain it. Core growth alone cannot answer that question.
The recovery is uneven
The same segment reconciliation shows:
| Segment | Reported sales growth | Core sales growth |
|---|---|---|
| Biotechnology | 0.5% | 5.0% |
| Life Sciences | 4.0% | 4.5% |
| Diagnostics | 17.0% | 0.5% |
Biotechnology’s bridge adds 0.5 percentage point for currency and 4.0 points for tariff refunds to reported growth. Calling the entire difference an acceleration in demand would therefore miss the accounting basis. Life Sciences’ half-point difference is the currency adjustment. Diagnostics removes 16.5 points for acquisitions/divestitures. A concrete acquisition behind the changed business perimeter is Masimo, which Danaher completed on 10 June 2026 and placed in Diagnostics. The reconciliation does not separately quantify Masimo’s contribution, so the entire combined adjustment should not be labelled Masimo alone.
Diagnostics grew 7.0% on a core basis excluding respiratory testing, versus 0.5% including it. The company’s bridge identifies a 6.5-point respiratory headwind within that segment. At total-company level, core growth excluding respiratory testing was 5.5%, versus 3.0% including it, a 2.5-point headwind. Segment and group contributions are not interchangeable.
The stronger excluded view is useful evidence about the rest of the business. But respiratory testing remains part of the actual business. Excluding weakness explains its location; it does not remove its effect on the investment outcome. Nor are these sales measures unit volumes, profit margins or proof that every geography and customer channel is improving.
Earnings provide a positive counterweight, with adjustments of their own
The EPS reconciliation reports $1.71 GAAP diluted EPS and $2.11 adjusted diluted EPS, a $0.40-per-share net gap. The corresponding prior-year figures were $1.27 and $1.89. These are continuing-operations measures. Danaher reports 11.5% growth in adjusted diluted EPS, faster than 3.0% core sales growth. That is positive counterevidence to a weak-growth-only reading, but it is per-share earnings growth, not total profit growth or proof of operating leverage: the earnings measure and core sales measure have different adjustment bases. The 11.5% figure is the issuer-reported growth rate; dividing the rounded $2.11 by $1.89 does not reproduce it exactly.
The current-quarter bridge is not one adjustment. It adds $0.73 for acquisition-related intangible amortization, $0.02 for investment losses, $0.12 for acquisition-related items, $0.07 for impairments and $0.02 for special equity awards. It subtracts $0.01 for an acquisition-contingency settlement, $0.17 for the tax effect of adjustments, $0.37 for discrete tax adjustments and $0.01 for rounding. Together, those entries reconcile $1.71 to $2.11.
The discrete-tax note identifies $263 million of net tax benefits, mainly reserve releases following audit settlements. This is a direct continuation of Monday’s profit-quality question: a discrete tax benefit supports headline earnings but is not recurring operating growth. That helped reported earnings; excluding it pulls adjusted EPS down, while other exclusions pull in the opposite direction. Neither amortization nor the tax benefit alone explains the net $0.40 gap. Adjusted EPS is useful for comparison, but is not a substitute for evaluating the economics of acquisition costs and other exclusions.
There is also constructive forward evidence: management raised full-year adjusted EPS guidance to $8.57–$8.62, from $8.45–$8.60. The lower bound rose $0.12 and the upper bound $0.02; the midpoint rose $0.07, from $8.525 to $8.595. That improves the company’s earnings outlook and matters to the earnings side of valuation. It complicates a simple negative reading of the sales bridge, although it is not an independently verified consensus beat or evidence that the current share price is attractive.
Q4 is the next observable test
For the quarter ending 31 December 2026, the company’s outlook calls for approximately 3% total core growth, or 4–5% excluding respiratory testing, with roughly 150 basis points of respiratory drag. The 4–5% ex-respiratory outlook is below Q3’s 5.5% actual growth on the same excluded basis. These are year-on-year growth rates for different quarters, not a forecast of a sequential sales decline. The rounded range and approximate drag should not be presented as an exact equation.
Management also guides to mid-single-digit Biotechnology core growth, 4–5% for Life Sciences, slightly positive Diagnostics growth and approximately 29.5% adjusted operating margin. These are forward-looking company estimates, not promises. Danaher does not provide a complete forward GAAP reconciliation because several adjustments cannot be reliably forecast.
Three tests follow from that guidance:
- Broader progress: core demand outside respiratory testing holds up and the respiratory drag moderates. The next results should show this in both the inclusive and excluded measures, not just a stronger headline.
- A narrower recovery: Biotechnology and Life Sciences remain positive, but Diagnostics’ total core growth stays weak. That would support improvement in parts of the business without establishing broad-based acceleration.
- A weaker outcome: non-respiratory growth or profitability misses the company’s own outlook. That would challenge the idea that the stronger parts can offset the weaker ones.
The practical question is what survives after consistent adjustments, and whether that translates into sustainable earnings and cash generation at an attractive price. This article does not establish a current fair value, use an unverified pre-release consensus, or claim a verified market-price reaction. It makes no new position or trade disclosure.
The earlier Costco sales analysis separated activity from profit. Monday’s JPMorgan work separated headline earnings from their supports. Danaher adds another discipline: inspect the definition of growth before deciding what the growth proves.
Which matters more next: stronger core demand or less respiratory weakness?
My portfolio and views, not investment advice.
@engtmk engtmk.com