American Express: adjusted earnings still need footnotes
By @engtmk · Research as of 23 October 2026
After JPMorgan’s profit comparisons and Danaher’s growth bridge, I am still asking what the headline leaves unexplained. American Express adds a useful complication: moving from reported to adjusted earnings does not finish the analysis.
This expands today’s published eToro post. My reading is constructive on demand, more cautious on profit conversion. The distinction matters when deciding what earnings deserve to be capitalised into a valuation.
Reconcile the headline first
The 23 October release, including Appendix I, covers the quarter ended 30 September 2026. Comparisons below are year on year unless specified. Guidance is a forecast, not a result.
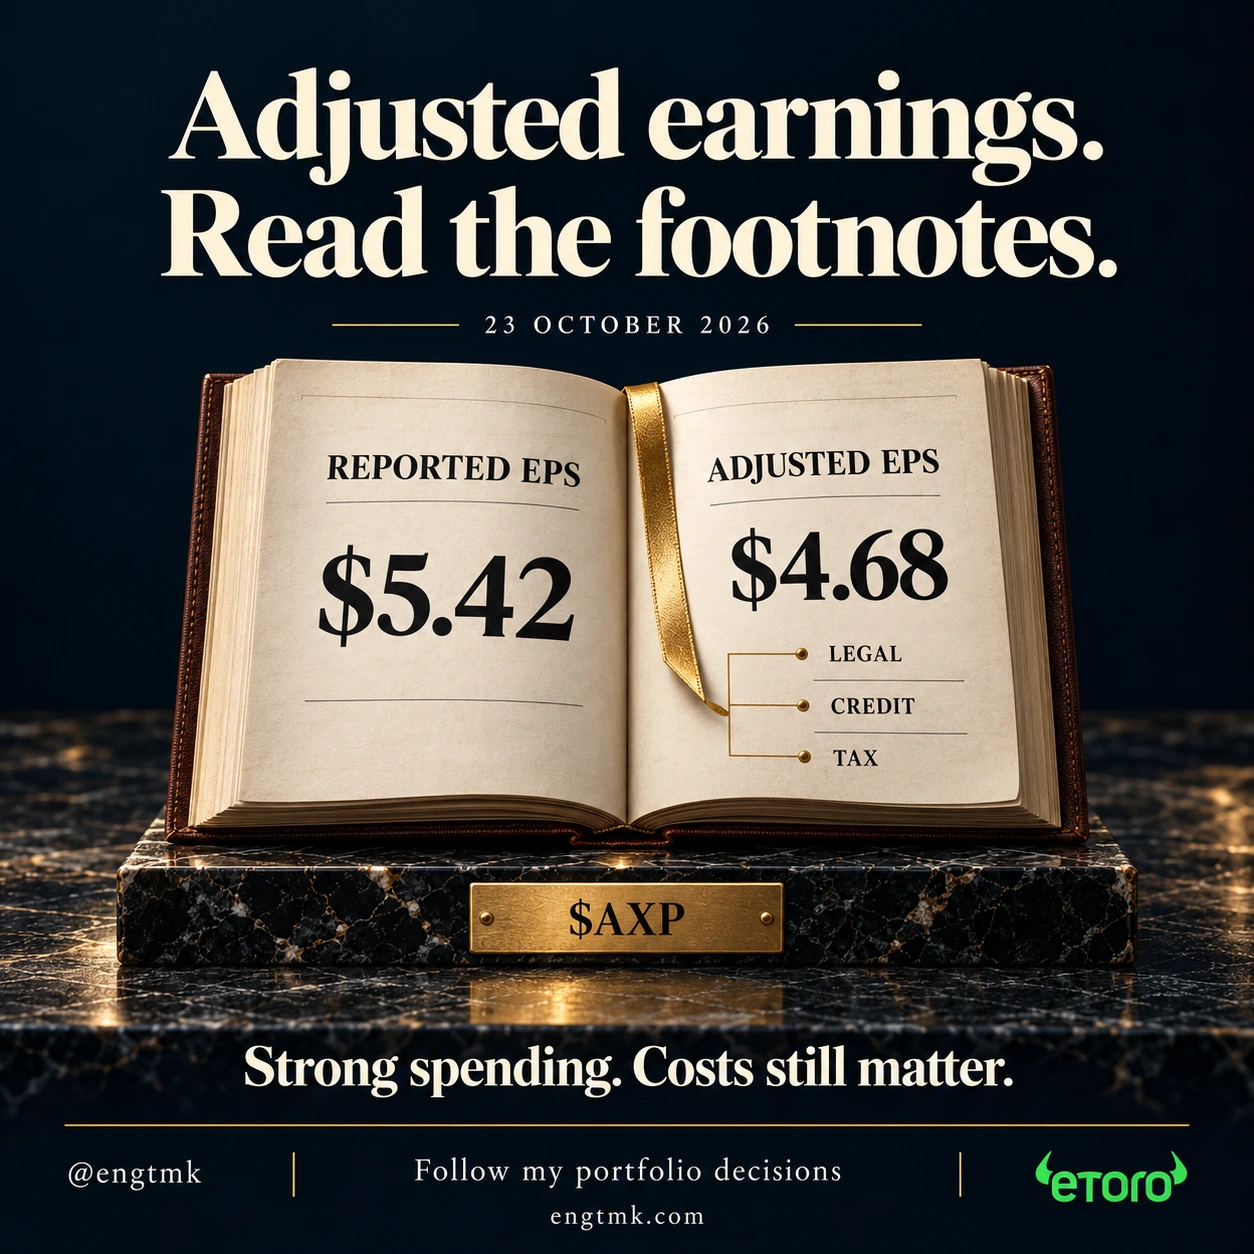
Reported diluted EPS was $5.42, versus $4.14, up 31%. The after-tax bridge is:
| Q3 EPS bridge | Dollars per share |
|---|---|
| Reported EPS | 5.42 |
| Remove Global Business Travel Group investment-sale gain | −1.11 |
| Add back restructuring charge | +0.37 |
| Adjusted EPS, non-GAAP | 4.68 |
The net difference is 74 cents, not $1.11. Adjusted EPS grew 13%. The company excluded both a gain and a cost; attributing the entire gap to one component would misstate the reconciliation.
The restructuring related to efficiency initiatives: $336m pretax, $253m after tax. The adjustment helps compare performance, but does not make that cost economically free. Equally, a sale gain is real value without necessarily being a repeatable source of quarterly earnings. The investment question is about persistence, not whether every adjustment is good or bad.
Adjusted does not mean free of notable items
Presentation slide 4 reports adjusted pretax income of $3.885bn, up 2%, adjusted net income up 11%, and adjusted EPS up 13%. Both reported and adjusted EPS retain:
| Notable item still included | EPS effect |
|---|---|
| Legal matters | −$0.51 |
| Expected-credit-loss model update | +$0.24 |
| Discrete tax item | +$0.29 |
Those three rounded effects net to about +2 cents, while their gross effects are much larger. They should not be ignored merely because they nearly offset, or used to claim that all earnings growth came from tax. Nor should the 2% pretax figure be relabelled fully recurring growth: it still includes the relevant pretax notable items.
The gap between pretax, net-income and per-share growth is a reason to inspect the stages separately. A shareholder receives per-share earnings, but durable operating improvement is a different question from a lower tax burden or a smaller share count.
The financial tables, page 1, show average diluted shares of 674m versus 693m. Fewer shares help per-share comparisons; they do not establish faster growth in the total earnings pool.
Demand is holding up; profit breadth is less convincing
The release reports revenue net of interest expense of $20.062bn, up 9%, and billed business of $454bn, up 8%. These are dollar measures, not inflation-adjusted transaction volumes.
The presentation, slides 13 and 17, adds net card fees of $2.969bn, up 16% reported. Rewards, business development and card-member services together cost $8.891bn, up 16%, or 44.3% of revenue. The growth-rate gap against revenue is seven percentage points, not a seven-point margin decline.
The release attributes higher engagement costs to spending and the U.S. Platinum refresh. Total expenses were $14.5bn, up 9%, matching revenue growth. Lower operating expenses primarily reflected the GBTG gain, partly offset by legal reserves and restructuring—not clean evidence of cost control.
This is the central trade-off. Benefits can help retain customers and support fees; they also need to earn their cost. Stronger spending is encouraging counterevidence to a collapsing-demand interpretation. It does not, by itself, demonstrate improving profitability.
Segment tables, page 7, show the uneven outcome:
| Segment | Q3 pretax income | YoY change |
|---|---|---|
| U.S. Consumer Services | $2.295bn | +24% |
| Commercial Services | $1.029bn | −6% |
| International Card Services | $432m | −2% |
| Global Merchant and Network Services | $1.082bn | +4% |
These are segment figures, not adjusted consolidated profit. Corporate and Other and consolidation must also be considered; summing only these four rows does not reproduce the group result. Consumer strength is important, but it does not justify describing profit improvement as uniform.
Credit offers another balanced check. The tables, pages 1 and 6, show provisions of $985m versus $1.287bn. Consumer/small-business principal-only write-offs were 1.8% versus 1.9%; 30-plus-day overdue balances were 1.2% versus 1.3%. These rates exclude corporate balances; the write-off rate excludes interest and fees. Better observed credit metrics are welcome, but the model benefit means provisions cannot be read as a pure measure of current borrower behaviour.
The guidance improvement is narrower than the headline suggests
Slide 21 keeps full-year revenue-growth guidance at 10%. Adjusted EPS guidance is $17.60–$17.90, compared with the $17.30–$17.90 EPS range in the 24 July Q2 release. The floor rises 30 cents; the ceiling is unchanged; the midpoint rises 15 cents. GAAP guidance is $18.30–$18.60.
The higher floor is positive evidence. It is not the same as lifting both ends or demonstrating that every extra dollar is operational. For valuation work, the useful next step would be to compare a defensible sustainable earnings range with the price being paid, rather than apply a multiple mechanically to the most flattering reported figure.
What would change the interpretation?
The next observable test is Q4 delivery and the next quarterly results: can the efficiency programme and Platinum investment translate into stronger pretax profit conversion? The restructuring charge establishes a cost incurred, not the amount or timing of future savings. I have not verified a future release date, so there is no calendar-day claim here.
- Stronger case: spending and fees remain healthy while customer-benefit costs become easier to absorb, with broader pretax progress. That would strengthen the case that the membership proposition is generating durable returns, rather than simply more activity.
- Mixed case: demand holds, but profit gains remain concentrated and the reported-to-adjusted bridge stays important. That would support business resilience without establishing stronger profit conversion.
- Weaker case: demand slows while costs remain elevated or credit deteriorates. That would challenge the idea that revenue momentum can comfortably fund the benefits offered to customers.
These are analytical scenarios, not forecasts or trades. This article does not claim a primary-source consensus beat, attribute an intraday price move to one cause, or establish a current fair value. No new holding, weight or performance disclosure is made.
The earlier Costco analysis asked whether sales would become profit. AXP sharpens that question: which part of profit is likely to recur, and what must the business deliver to sustain it?
What would convince you that the Platinum investment and efficiency programme are improving sustainable pretax profit?
My portfolio and views, not investment advice.
@engtmk engtmk.com